Managing household expenses while trying to build long-term independence can feel like a constant balancing act. Between digital subscription traps, shifting grocery costs, and persistent wage gaps, keeping tight control of your monthly cash flow is essential.
Fortunately, finding effective ways to save money doesn’t require turning your lifestyle upside down or cutting out every simple pleasure. Small, strategic adjustments to your daily routine can quickly unlock hidden room in your budget.
In this guide, you’ll discover 5 actionable habits to cut unnecessary expenses, optimize everyday bills, and start keeping more of your hard-earned paycheck—starting today.
1. Audit Your Subscriptions & Bills for Immediate Monthly Cash Flow
If you haven’t reviewed your recurring expenses in the last six months, you are almost certainly paying a “convenience tax.” Service providers, streaming platforms, and utility companies routinely increase rates quietly, relying on automatic payments to keep customers from noticing.
Taking 30 minutes to audit your fixed monthly expenses is one of the fastest ways to save money without impacting your quality of life.
Call Your Providers Using a 3-Step Negotiation Script
Most people avoid calling service providers (internet, cable, phone, insurance) because it feels awkward or tedious. However, customer retention departments are explicitly authorized to give discounts to keep you from switching to a competitor.
Use this proven, 3-step script framework on your next call:
- Establish Loyalty & Set the Context: “I’ve been a loyal customer for [X years], but my monthly bill has gotten too high for my current budget.”
- Mention Competitor Offers: “I noticed [Competitor Name] is offering a similar plan for $[Lower Amount] per month.”
- Ask for Retention Discounts Directly: “What options or promotional rates can you apply to my account today so I can stay with you?”
Pro Tip (Real-Life Savings): Negotiating internet and phone bills once a year typically yields an immediate $20–$50/month in savings—freeing up to $600 annually in less than a 15-minute phone call.
Trim Hidden Subscriptions and Unused Memberships
Micro-subscriptions—from $4.99 app trials to forgotten streaming add-ons—are designed to drain cash flow unnoticed.
To catch these hidden leaks fast:
- Run a 90-Day Statement Search: Log into your primary checking account or credit card dashboard and search for keywords like
"recurring","subscription","membership", or"trial". - Use the “Cancel First, Re-subscribe Later” Rule: If you haven’t used a streaming service or gym membership in the last 30 days, cancel it immediately. You can always reactivate it later if you genuinely miss it—though most people never do.
- Audit Digital Wallets: Open Apple Pay or Google Wallet on your phone and review active in-app subscriptions that don’t show up on traditional bank statements.
2. Cut Grocery Costs Without Giving Up Your Favorite Foods
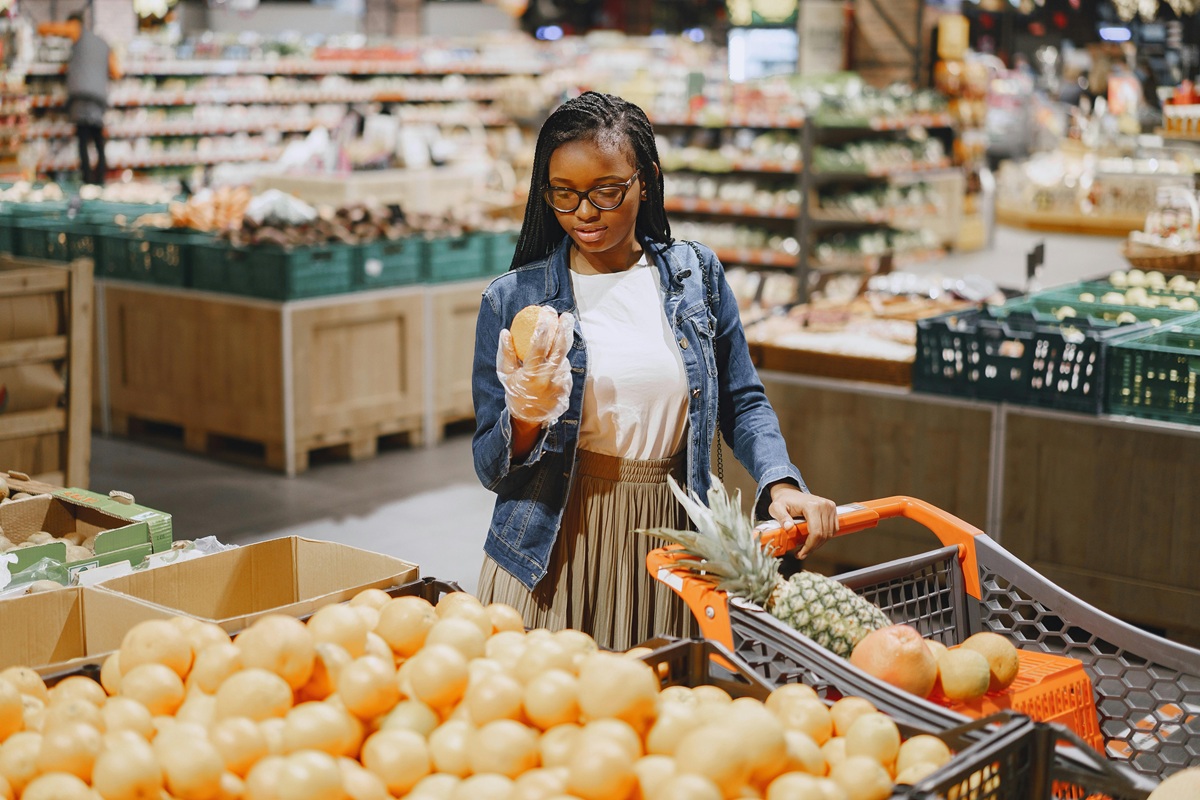
Food inflation remains one of the largest variables in any household budget, but trimming your food bill doesn’t mean eating boring meals or sacrificing quality. The key is shifting from reactive shopping to strategic inventory management.
By making a few tactical shifts before you step into the store, you can easily shave 20% to 30% off your register total while still enjoying your weekly favorites.
Shop Your Pantry First with a Reverse Meal Plan
Traditional meal planning often starts by picking recipes online and buying a long list of new ingredients—leaving half-used jars and unused produce to rot in the fridge.
A “reverse meal plan” flips this process to eliminate food waste and instant cash leaks:
- Take Inventory First: Spend 5 minutes auditing your fridge, freezer, and pantry. Take note of proteins, grains, and canned goods that need to be used soon.
- Build Meals Around Existing Base Ingredients: Search for recipes using what you already own. If you have black beans, rice, and salsa, your shopping list only needs tortillas and fresh cilantro for taco night.
- Shop Only for Missing Bridge Items: Buy only the fresh produce or dairy needed to complete those meals.
Stack Digital Store Coupons with Store-Brand Alternatives
You no longer need to clip paper coupons to get dramatic savings at the checkout counter. Combining digital loyalty perks with smart product swaps creates instant, compounding discounts.
- Clip Digital Coupons Before Opening the Store Door: Download your primary grocery store’s app. Spend two minutes clipping digital offers—especially for pantry staples, paper goods, and household cleaners—before adding items to your cart.
- Embrace the 25% Generic Swap: Store-brand (private-label) staples—such as canned tomatoes, oats, spices, and baking supplies—are usually manufactured by the exact same brand-name producers, but cost 20% to 30% less due to minimal marketing overhead.
- Check Price Per Unit: Always look at the small print on the store shelf tag showing the cost per ounce or per gram. Bulk options or store brands frequently beat “sale” prices on smaller brand-name items.
Smart Shopping Swaps for Instant Monthly Savings
| Conventional Shopping Habit | Smart Tactical Swap | Estimated Monthly Savings |
|---|---|---|
| Buying Name-Brand Staples (spices, canned goods, grains) | Store-brand / private-label equivalents | $30 – $45 |
| Unplanned Daily Grocery Runs | 1 weekly planned trip using a reverse meal list | $40 – $75 |
| Pre-Cut Fruits & Pre-Washed Veggies | Whole produce (cut at home) | $15 – $25 |
| Shopping Without Store App Offers | Stacking digital manufacturer coupons with store rewards | $20 – $40 |
3. Automate Your Savings to Build a Safety Net on Autopilot
Relying on willpower to save money at the end of the month almost never works. By the time bills, groceries, and daily coffee runs are accounted for, there is rarely anything left over. The secret to consistently building an emergency fund is removing human decision-making entirely, turning wealth-building into an effortless background process.
The most effective strategy is to Pay Yourself First: treat your savings like a non-negotiable monthly bill that gets paid the exact moment your income arrives, rather than saving whatever happens to be left over.
- Set Up Payday Transfers: Schedule an automatic transfer from your checking to your savings account for every payday. Starting with just $25 to $50 per paycheck quietly builds a $600–$1,200 annual buffer without impacting your day-to-day lifestyle.
- Leverage High-Yield Accounts: Keep your emergency savings in a High-Yield Savings Account (HYSA) earning 4%–5% APY instead of a traditional bank’s 0.01%. On a $5,000 balance, this single switch yields $200–$250 in free passive interest every year.
- Create Friction: Keeping your savings at a separate bank from your primary checking account adds a 24-hour transfer delay—a simple boundary that effectively halts impulse withdrawals.
- Enable Micro-Round-Ups: Use banking apps that round up every debit or credit card transaction to the nearest dollar and sweep the spare change into savings. A $4.35 morning coffee automatically saves $0.65, generating $30 to $60 in extra monthly savings completely on autopilot.
4. Stop Digital Impulse Spending with the 24-Hour Rule
One-click ordering, targeted social media ads, and saved payment details make spending money online almost frictionless. Marketers spend millions designing experiences that bypass your logical brain, turning temporary wants into instant purchases.
Implementing a mandatory 24-hour pause breaks the impulse loop, restoring control over your daily spending habits without feeling deprived.
Remove Saved Credit Cards from Online Stores
Convenience is the biggest driver of online impulse buying. When your payment details and shipping address are auto-filled, buying a $45 sweater takes less than three seconds—leaving no time for rational evaluation.
- Delete Auto-Fill Payment Details: Remove stored credit cards from Amazon, Target, retail apps, and browser settings (like Chrome or Safari).
- Create Intentional Friction: Forcing yourself to physically retrieve your wallet, pull out your card, and type in 16 digits introduces just enough effort to make you question if the purchase is truly necessary.
- Unsubscribe from Marketing Emails: Retailers use “flash sales” and “exclusive 20% off” emails to create artificial urgency. Use the search bar in your inbox to search
"unsubscribe"and clear out major shopping lists.
Pro Tip (The Cart Test): When shopping online, add items to your cart and close the tab immediately. Over 70% of the time, the urge to buy vanishes by the next day—and retailers will often email you a 10%–15% discount code just for leaving the items behind.
Identify Your Emotional Spending Triggers
Impulse shopping is rarely about needing the physical item; it is almost always an emotional reaction to stress, boredom, or target-driven social media trends.
- Track the “Why” Behind Purchases: Before completing any non-essential purchase, take 10 seconds to score your mood. Are you buying out of stress, fatigue, or seeking a quick dopamine hit after a hard workday?
- Swap the Retail High with Free Rewards: Replace the habit loop. If you turn to online browsing to unwind, replace it with a non-monetary reset—like taking a short walk, saving inspiration on a Pinterest board, or calling a friend.
- Calculate Cost in Work Hours: Convert an item’s dollar price into your actual hourly take-home pay. Asking yourself, “Is this $80 pair of shoes worth 4 full hours of work?” instantly puts the purchase in perspective.
5. Maximize Cash-Back, Rewards, and Apps for Instant Savings
If you are paying full price for everyday essentials, you are leaving money on the table. Cash-back platforms, loyalty apps, and reward strategies allow you to claw back a percentage of the money you are already spending on groceries, fuel, household supplies, and online purchases.
By systematically stacking these tools, everyday expenses transform into a consistent stream of passive savings.
Activate Cash-Back Offers Before Every Purchase
The biggest mistake shoppers make with rewards platforms is assuming discounts happen automatically. Maximizing cash-back requires turning pre-purchase activation into a 10-second habit.
- Use Browser Extensions for Online Shopping: Install free cash-back extensions (like Rakuten or Capital One Shopping). They automatically alert you to cash-back percentages and apply active coupon codes at checkout with a single click.
- Scan Receipt Apps Post-Grocery Run: Platforms like Fetch or Ibotta allow you to upload paper or digital receipts after shopping, earning points that redeem directly for gift cards or cash via PayPal.
- Link Loyalty Accounts: Connect your primary grocery and pharmacy rewards numbers directly to cash-back apps to automate earnings without needing to manually upload receipts every time.
Combining a standard 2% cash-back credit card with a 3% cash-back browser portal yields a total 5% return on online purchases. On an average household online spend of $400/month, that simple double-dip generates $240 in cash-back every year.
Stack Rewards With Store Discounts for Bigger Savings
To extract maximum value from rewards programs, apply the “Stacking Method”—layering multiple savings mechanisms onto a single transaction.
- Layer 1: Store Sales & Clearance Items: Start by selecting items already on sale or marked down in-store.
- Layer 2: Digital Store Coupons: Apply store app digital coupons or paper manufacturer vouchers to the discounted price.
- Layer 3: Cash-Back Payment Method: Pay using a credit card that offers elevated rewards for that specific category (e.g., 3%–6% back on groceries or gas).
- Layer 4: Third-Party Receipt Scan: Upload the final receipt to a cash-back app to earn bonus points on top of your credit card and store rewards.
Frequently Asked Questions
How can I save money quickly?
To quickly save money within 24 to 48 hours, audit your recurring leaks rather than overhauling your entire lifestyle. Search your bank statements for hidden subscription charges to cancel, call your phone and internet providers to request retention discounts, and enforce an immediate 24-hour pause on non-essential online purchases.
How can I save money when I have very little income?
If you are operating on a tight income, focus on micro-habits rather than rigid dollar targets. Start by setting aside as little as $5 or $10 a week, enable automated spare-change round-ups on daily purchases, and keep your balance in a High-Yield Savings Account so every dollar earns maximum interest without financial strain.
What is the fastest way to cut monthly expenses?
The single fastest way to cut monthly expenses is by targeting your largest variable cost: food and groceries. You can immediately lower your outflow by adopting a “reverse meal plan” using ingredients you already own, swapping name-brand items for store-brand alternatives, and pausing takeout or delivery orders for 30 days.
How much money should I try to save each month?
While standard personal finance guidelines recommend saving 20% of your take-home pay, the right amount ultimately depends on your current budget margin. If you are starting out, aim for 5% to 10% until you build an initial safety net, and scale up toward 15% to 20% as your cash flow allows—the key is choosing a consistent rate that does not force you to rely on credit cards.
Small Steps Today, Big Financial Momentum Tomorrow
Taking control of your finances doesn’t require a complete lifestyle overhaul or drastic sacrifices. By auditing your recurring bills, shopping with a plan, automating your savings, and pausing impulse buys, you can easily free up hundreds of dollars every month. The secret is consistency—start with just one or two of these tactics today, lock in your quick wins, and build momentum toward long-term financial independence.
For an easy way to stay consistent, check out 10-Minute Money Tracking Made Simple for Women.
What’s your next move? Choose one expense on your bank statement right now, make the quick adjustment, and watch your safety net grow on autopilot.
By Aveline Lowell
Founder & Editor-in-Chief, RiseByHer
Aveline Lowell writes research-driven content covering women’s finance, entrepreneurship, STEM, technology, and career growth. Her work focuses on practical, well-researched information that helps women make informed decisions.
Editorial & Disclaimer: RiseByHer aims to provide accurate, well-researched, and up-to-date information. Articles are reviewed and updated when necessary and are intended for general informational and educational purposes, not personalized financial, legal, tax, or professional advice.